All Categories
Featured
Table of Contents
To reverse a decade of deteriorating overall aspect performance, regional labour market policy is shifting from basic job development to handling active labor force shifts. Federal governments and employers are scaling short, modular training programmes and micro-credentials in information analytics and digital operations to gear up workers for emerging functions. Workplace-based knowing and apprenticeship-style paths are ending up being more common as firms integrate AI tools into day-to-day workflows.
With oil prices anticipated to average $55-60 per barrel in 2026, regional federal governments are heightening their focus on expense discipline and private capital mobilisation. Financial policy is pivoting toward the monetisation of state-owned properties in logistics, utilities, and desalination to reroute funds toward higher-impact investments. While loaning through sukuk and sustainability-linked bonds is expected to increase to money tactical deficits, the focus stays on strengthening non-oil revenue frameworks.
PwC Middle East economic policy and method partner Jing Teow stated: "Having currently mobilised capital and policy at scale, GCC governments are now focused on shipment. In 2026, the top priority is enhancing economic durability through more secure trade and financial investment relationships, effective AI release, managed workforce transitions and disciplined fiscal policy in a more tough and fragmented international environment.".
Saudi Arabia and UAE are poised to lead the Gulf region's economic expansion in 2026, supported by strong private-sector efficiency, resistant domestic demand and restored investment momentum, according to the current ICAEW Economic Insight Q4 2025 report, produced by Oxford Economics. The GCC is expected to surpass most global areas peers next year, with regional GDP projection to grow by 4.4%. Across the GCC, non-energy activity is predicted to expand by 4.1% in 2026, driven by strong labour markets, enhancing credit conditions and increasing financial investment in innovation and AI-related infrastructure.
Although oil earnings will be under pressure in the first half of 2026, production is anticipated to increase again in the second half of 2026, supporting the area's medium-term outlook, it specified. Saudi Arabia will remain a significant contributor to GCC momentum, with GDP forecast to grow 4.3% in 2026.
Essential Tips for Operational Excellence in the GCC
Development will be supported by commercial growth and policy reforms, consisting of relieved foreign ownership guidelines that aim to promote more financial investment. The financial deficit is forecasted to broaden to 5.6% of GDP next year amidst softer oil costs, while the recent five-year rent freeze in Riyadh aims to alleviate inflationary pressures, though it might constrain future housing supply.
Strong domestic fundamentalsThe UAE is also placed for another strong year of efficiency, with GDP forecast to increase 5.6% in 2026 as non-oil sectors continue to expand. Tourism, trade and monetary services remain crucial growth drivers, supported by population growth and continual domestic demand. Dubai's economy grew 4.4% in the first half of 2025, reflecting broad-based non-oil strength.
Oil production is anticipated to get once again in the second half of 2026, complementing ongoing financial investment in infrastructure, innovation and worldwide trade collaborations. Hanadi Khalife, the Head of Middle East, ICAEW, stated: "This quarter's outlook reinforces how far the GCC has can be found in structure varied, durable and worldwide competitive economies.
Achieving Process Excellence in the Industrial SectorScott Livermore, ICAEW Economic Consultant, and Chief Financial Expert and Handling Director, Oxford Economics Middle East, stated: "Saudi Arabia and the UAE are going into 2026 with strong foundations. Saudi non-oil activity is gaining pace, supported by robust need and rising financial investment, even as financial pressures increase.""The UAE continues to benefit from solid domestic principles, a sharp uplift in government spending and sustained diversity efforts.
Enterprise Agility for the Changing GCC LandscapeEmerging Strategic Trends Defining the 2026 Regional Economy
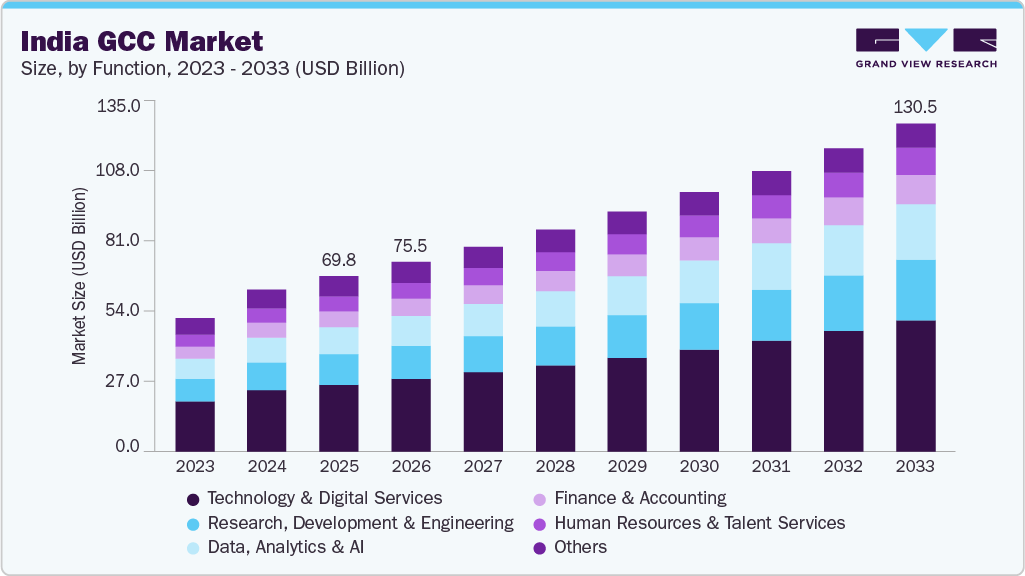
What differentiates 2026 from preceding years is not simply the velocity of technological modification, though that velocity is real, but rather an essential shift in how enterprises conceive of their GCCs' purpose. The is expected to grow to four hundred thirteen billion dollars by 2040, however this development masks a more extensive transformation.
Instead, they ask whether these centers drive development, own profit-and-loss responsibility, and contribute to competitive differentiation. In 2026, the most successful GCCs will act like internal startups, agile, cross-functional, insight-driven, and deeply lined up with global company outcomes. This shift from execution to ownership represents maybe the single most considerable tactical recalibration in the GCC model's development.
Today, we're convening more than 3000 conferences between investors and 119 Gulf-listed companies with a combined worth of $2.4 trillion at the HSBC GCC Exchanges Conference 2026, in London. We're bringing together financiers, companies, exchanges, and policymakers to discuss what is changing in the area, and what follows, consisting of the growth and ongoing advancement of the Gulf's capital markets, and the region's growing function in worldwide networks of capital and trade.

Latest Posts
Will the GCC Sustain Industrial Growth during 2026?
How to Successfully Implement Future Strategies for 2026
Middle East Economic News and Strategic Realities